September 20, 2026
2026 Ferroalloy Industry Trends | Market Analysis & Global Export Outlook
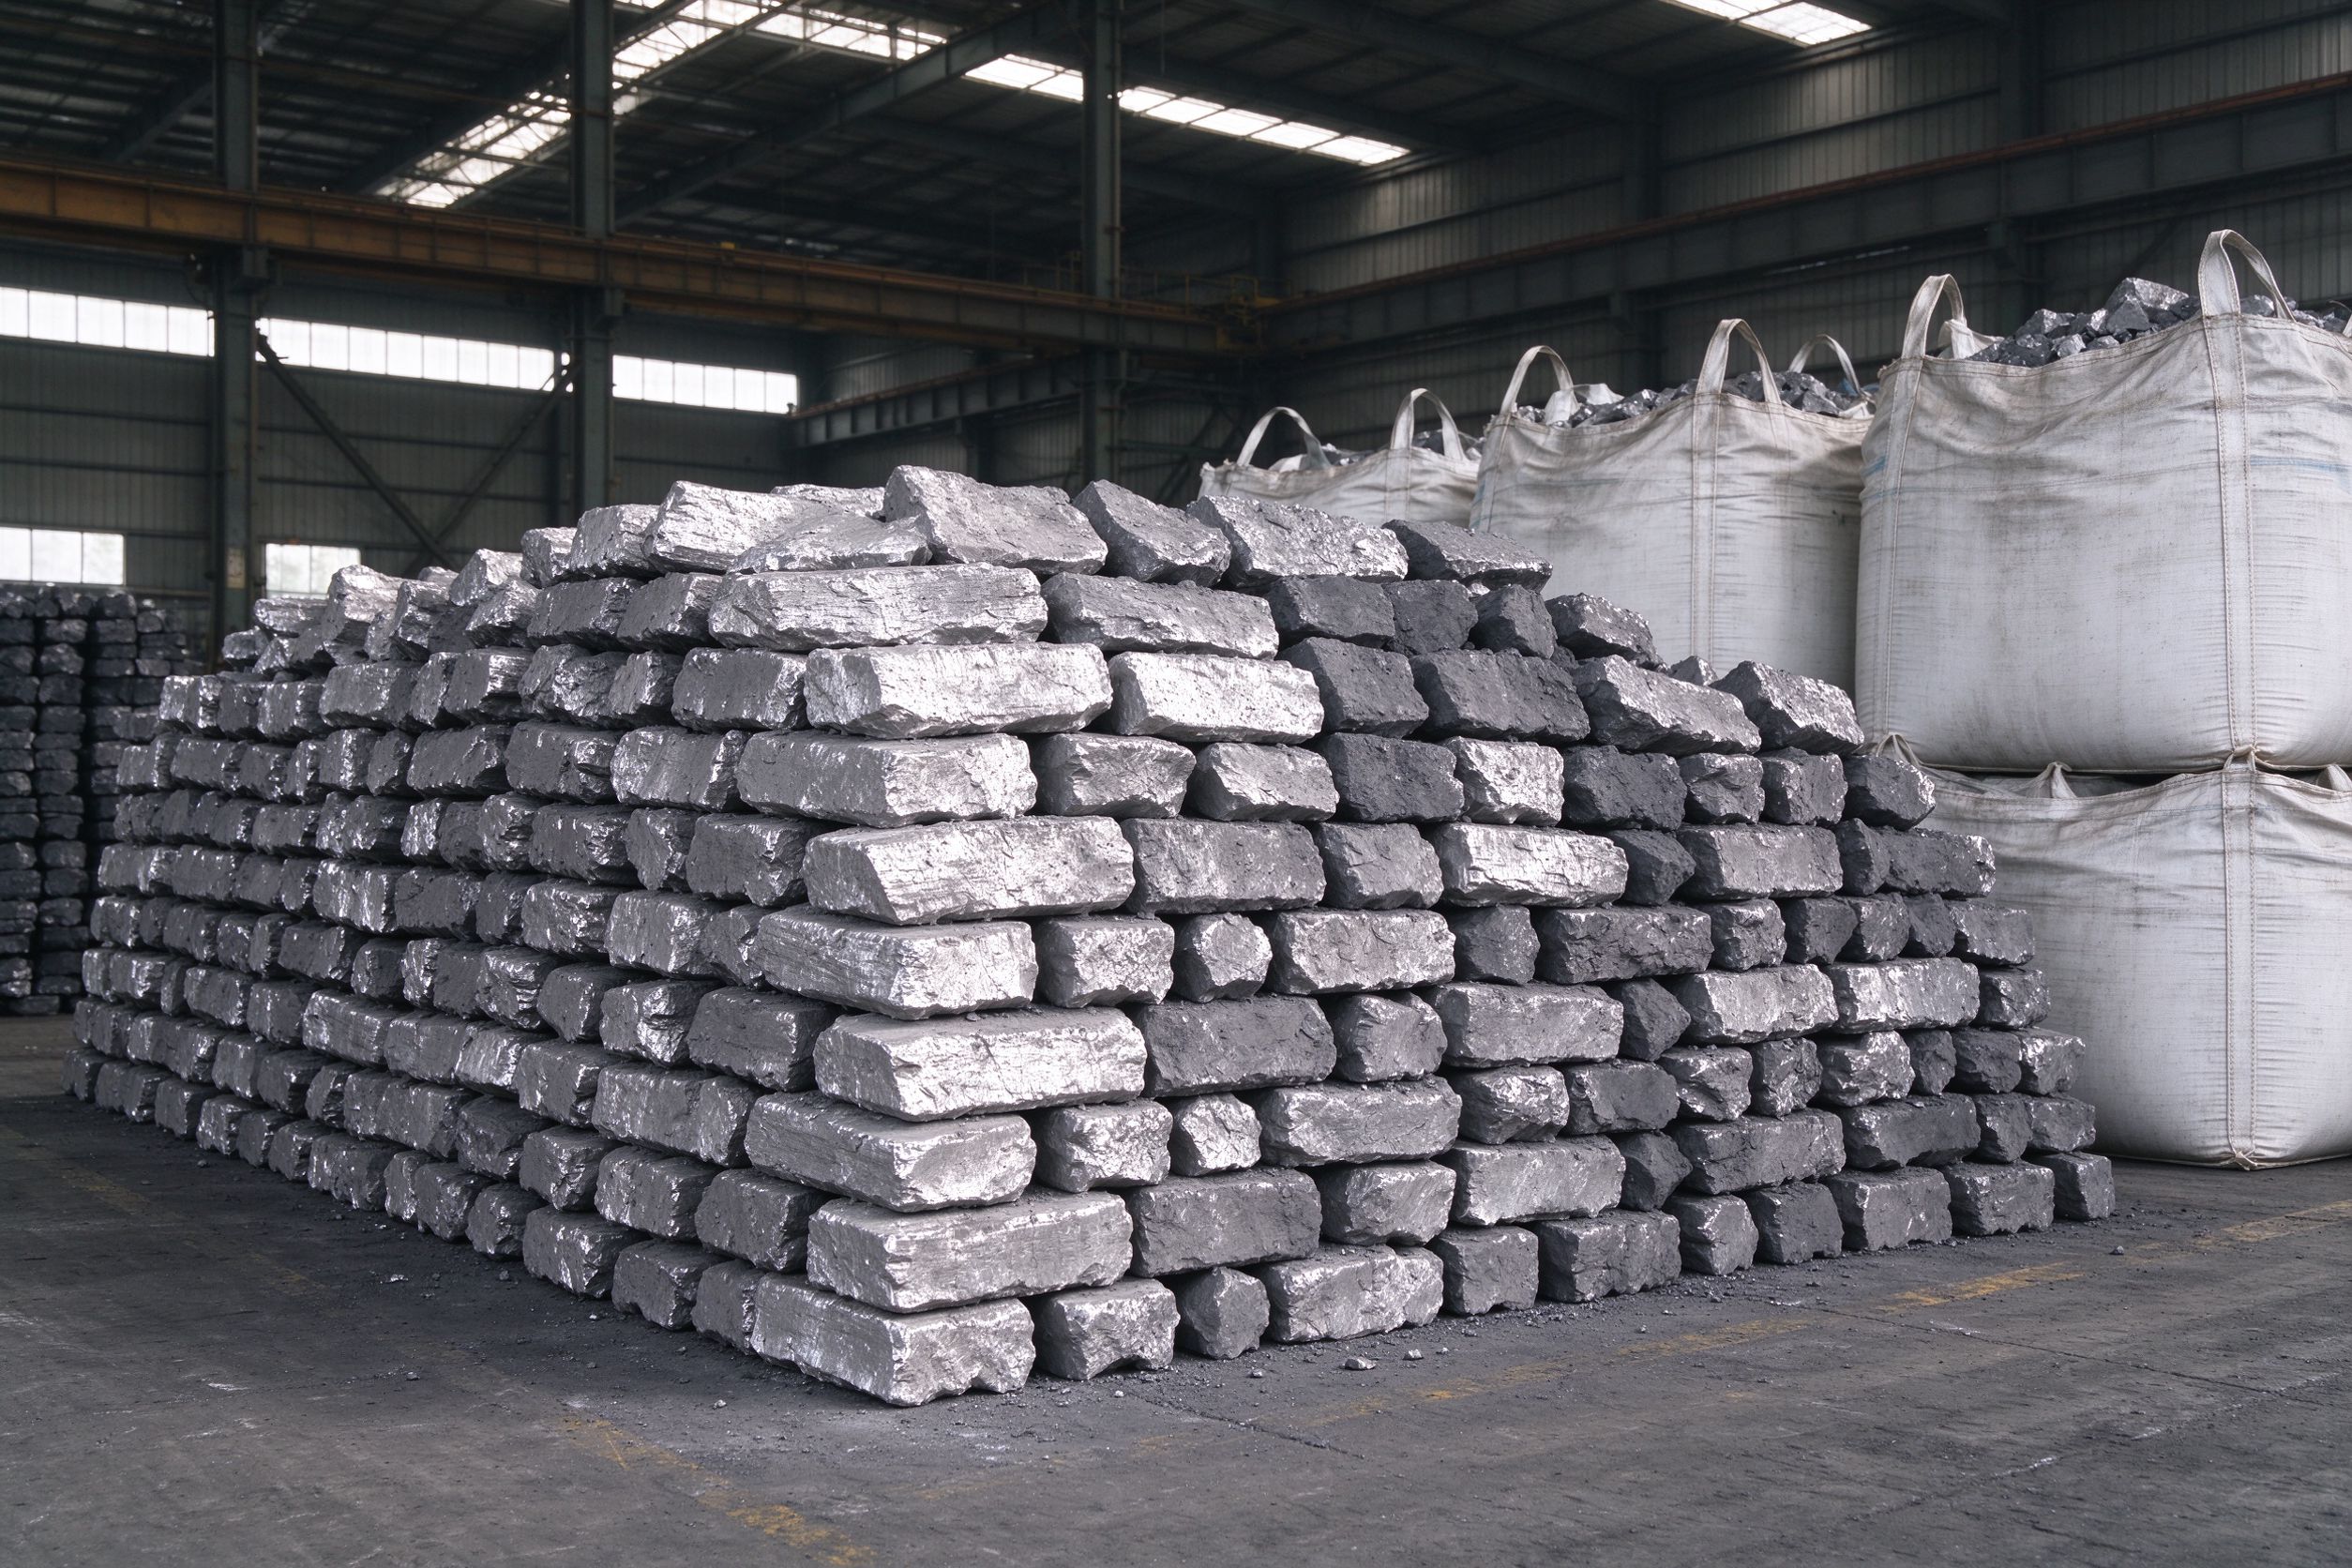
The global ferroalloy industry is experiencing major structural upgrades in 2026. Affected by low-carbon policies, volatile energy costs and upgraded steelmaking standards, the industry is phasing out backward capacity and shifting from low-end capacity expansion to high-purity, low-carbon and customized high-value production. The market shows clear product differentiation. Conventional industrial-grade ferrosilicon, silicon manganese and ferrochrome face overcapacity and fierce price competition. By contrast, high-purity, ultra-low sulfur and ultra-low phosphorus ferroalloys are in tight supply, widely applied in special steel, new energy vehicles, wind power equipment and precision casting with stable profit margins. Green low-carbon transformation is the core industry trend in 2026. As international carbon tariffs and green manufacturing standards take effect, energy-saving smelting technologies and standardized environmental production have become core competitive advantages. Non-compliant manufacturers are being eliminated, further standardizing the global ferroalloy supply chain. China remains the world’s core ferroalloy production and export base. In 2026, overseas demand grows steadily across Southeast Asian infrastructure projects, European high-end steel manufacturing and Middle Eastern new energy industries. Global buyers now prioritize stable batch quality, complete certifications and professional one-stop export services over low prices alone. Moving forward, the ferroalloy industry will focus on three key directions: high-end product upgrading, green...
Learn more